Key Points
- Investment Slowdown: Norges Bank Investment Management (NBIM), which manages Norway’s $2.3 trillion sovereign wealth fund, has dramatically scaled back its capital deployment in unlisted renewable energy infrastructure this year due to inflated asset prices.
- Significant Drop in Capital Deployment: After investing roughly €11 billion ($12.3 billion) in renewable energy infrastructure assets last year, the fund has committed just “north of €2 billion” in new money during the current period.
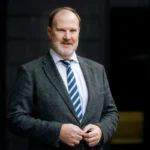
- Executive Assessment: Harald von Heyden, Global Head of Energy and Infrastructure at NBIM, confirmed that high asset valuations across the clean energy market are currently preventing the fund from accelerating its investment pace as intended.
- Under-Allocation Relative to Mandate: Unlisted renewable energy infrastructure continues to represent a minor fraction of the fund’s total portfolio, remaining well below the maximum 2% allocation cap permitted by the Norwegian parliament.
- Disciplined Capital Strategy: The fund is maintaining strict return targets and price discipline rather than compromising on valuation metrics to meet broader green energy deployment goals.
Norway (Norway Post Magazine) November 9, 2026 – Norway’s $2.3 trillion sovereign wealth fund has hit a major obstacle in its ambition to expand investments in renewable energy infrastructure, warning that high asset valuations across the green energy sector are holding back capital deployment. As reported by financial press agency Bloomberg on Monday, 9 November 2026, Norges Bank Investment Management (NBIM) has seen its pace of new investments drop sharply compared to the previous year. Speaking on the market conditions facing institutional investors, Harald von Heyden, Global Head of Energy and Infrastructure at NBIM, revealed that after plowing approximately €11 billion ($12.3 billion) into renewable assets last year, the fund has committed only “north of €2 billion” in new capital during the current cycle due to overpricing in the market.
- Why Is Norway’s Sovereign Wealth Fund Scaling Back Renewable Energy Deployments?
- How Does Current Allocation Compare to Norway’s Strategic Targets?
- What Strategy Is NBIM Pursuing Amid Market Overpricing?
- Background of the Particular Development After the News
- How This Development Can Affect Renewable Developers, Capital Markets, and Institutional Investors
Why Is Norway’s Sovereign Wealth Fund Scaling Back Renewable Energy Deployments?
According to reporting by financial reporters covering global asset management, the sharp decline in deal flow is not due to a change in long-term strategy, but rather a direct response to market pricing dynamics.
Harald von Heyden of NBIM explained that while the fund maintains a strong mandate to build out its portfolio of unlisted renewable energy assets, current entry valuations do not align with the fund’s strict risk-return requirements.
High competition among institutional investors—including pension funds, private equity firms, and state-backed infrastructure vehicles—has driven up prices for operational wind, solar, and energy storage assets worldwide.
As reported by Bloomberg, Harald von Heyden stated that while the sovereign wealth fund wants to accelerate its allocations to renewable energy infrastructure, those efforts are currently being stymied by the price of available assets.
The disparity in capital deployment is stark:
- Previous Year Deployment: Approximately €11 billion ($12.3 billion) directed into unlisted renewable energy infrastructure projects.
- Current Year Deployment: Slightly above €2 billion in new commitments, representing an over 80% drop in new capital deployment.
- Allocation Cap: The Norwegian parliamentary mandate allows NBIM to invest up to 2% of the fund’s total value in unlisted renewable infrastructure, but actual holdings remain far below this limit.
How Does Current Allocation Compare to Norway’s Strategic Targets?
As reported by Bloomberg and confirmed in operational filings by NBIM, unlisted renewable energy infrastructure remains the smallest asset class in the fund’s multi-trillion-dollar portfolio.
While the fund holds significant positions in global equities, fixed-income instruments, and unlisted real estate, unlisted renewables account for less than 1% of total assets, hovering near 0.5%.
In 2019, Norway’s parliament formally expanded the fund’s management mandate to permit direct investments in unlisted renewable infrastructure—such as offshore wind farms, solar parks, and power transmission assets—without requiring a partner company listed on a public stock exchange.
The mandate was designed to give the world’s largest single owner of corporate stock room to capture long-term yields generated by the global energy transition.
However, fund managers have repeatedly emphasized that they will not rush capital into high-priced projects simply to hit statutory allocation ceilings.
Instead, NBIM continues to exercise caution, refusing to lower its discount rate or accept squeezed yield margins in an environment characterized by elevated interest rates and persistent supply chain costs for clean energy components.
What Strategy Is NBIM Pursuing Amid Market Overpricing?
According to analysis of recent transaction records by financial press outlets, NBIM is shifting toward highly selective co-investments and targeted platform acquisitions rather than participating in broad competitive auctions for mature assets.
Rather than overpaying for operational utility-scale wind and solar farms in overcrowded North American and Western European markets, the fund has sought out strategic partnerships with established global infrastructure operators.
Recent strategic moves by the fund include:
- Co-Investment Agreements: Partnering with major global asset managers to acquire direct stakes in specialized energy transition developers, such as energy storage platforms.
- Geographic and Technological Expansion: Exploring direct and indirect structures in newer sub-sectors, including power distribution grids, battery storage systems, and selective emerging market infrastructure.
- Value-Oriented Discipline: Maintaining a high return hurdle rate to ensure unlisted real assets deliver superior risk-adjusted returns compared to public green equities.
By remaining disciplined on asset pricing, von Heyden and the NBIM leadership team aim to protect the fund’s capital until valuation multiples in the global renewable market return to more sustainable levels.
Background of the Particular Development After the News
The management of Norway’s sovereign wealth fund—officially named the Government Pension Fund Global and funded by state revenues from petroleum extraction—has historically maintained a reputational benchmark for rigorous institutional discipline. When the Norwegian Storting (parliament) authorized the fund to invest up to 2% of its portfolio in unlisted renewable energy infrastructure, climate advocates and global financial institutions anticipated a massive influx of capital into green projects worldwide.
However, the global renewable energy infrastructure market underwent severe structural shifts between 2022 and 2026. A combination of rising central bank interest rates, surging engineering, procurement, and construction (EPC) costs, equipment supply chain bottlenecks, and regulatory delays created valuation discrepancies across the sector. While project developers sought high sales prices to cover inflated construction and capital costs, institutional investors like NBIM faced higher risk-free yields in government bonds, demanding higher capital returns from real assets. As a result, many large-scale renewable projects became overpriced relative to their projected cash flows, leading conservative sovereign wealth managers to pull back on bidding.
How This Development Can Affect Renewable Developers, Capital Markets, and Institutional Investors
The decision by the world’s largest sovereign wealth fund to pull back from overpriced renewable infrastructure will have direct consequences across global financial markets and the clean energy sector.
Impact on Renewable Energy Project Developers and Asset Vendors
For green energy project developers, utility companies, and private equity sponsors seeking to divest operational wind and solar portfolios, NBIM’s pricing pushback signals the end of unrestrained asset price inflation. Sellers will no longer be able to count on deep-pocketed sovereign wealth funds outbidding the market for low-yielding green assets. To secure institutional capital, developers will need to adjust price expectations downward or offer higher yield structures to attract top-tier investors.
Impact on Global Renewable Energy Investment Flows
For global climate finance targets and renewable energy infrastructure deployment, the temporary slowing of sovereign capital deployment creates a short-term capital bottleneck. With a $2.3 trillion fund holding back billions of dollars in potential allocations, project developments that rely on institutional co-investment may face delayed financial closings or require higher debt ratios to proceed, potentially slowing the pace of power grid decarbonization in developed markets.
Impact on Institutional Asset Managers and Infrastructure Funds
For institutional asset managers, pension funds, and sovereign peers, NBIM’s disciplined stance sets a powerful market precedent. Financial institutions that felt competitive pressure to deploy capital into green mandates regardless of price will likely adopt similar valuation discipline. This shift will encourage a market repricing across unlisted real assets, eventually bringing valuation multiples down to levels where major long-term institutional investors can resume large-scale capital deployment safely.